Granite Real Estate Investment Trust Closes $270.5M in Houston and UK Distribution Acquisitions
Granite Real Estate Investment Trust (TSX: GRT.UN) announced the closing of $270.5 million of new distribution property acquisitions across Houston and the United Kingdom, alongside its third-quarter 2026 results and a 4.23% increase to its targeted annualized distribution. The Toronto-based trust made the announcement on November 4, 2026.
The four acquisitions comprise approximately 1.2 million square feet of fully leased, modern logistics space, acquired at going-in yields ranging from 5.3% to 6.0%. The blended purchase price works out to approximately $225 per square foot.
Granite REIT Houston Acquisitions: Two Northwest Submarket Assets
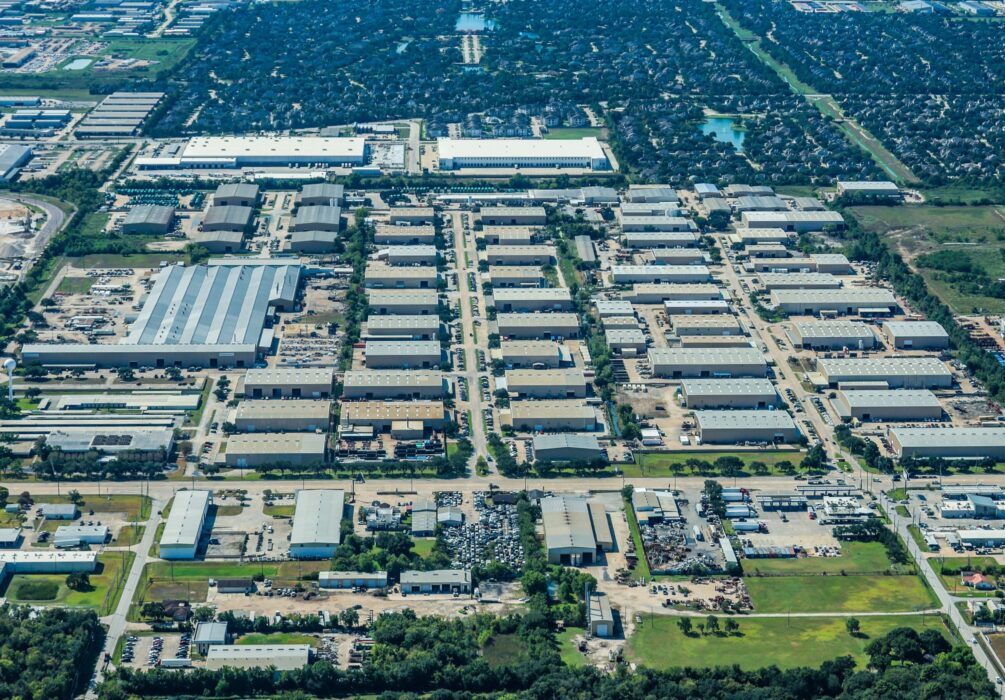
Granite acquired two properties in Houston's Northwest submarket in August 2026. On August 20, it purchased 6411 N. Eldridge Parkway, a roughly 500,000-square-foot distribution facility, for $104.1 million (US$75.6 million), or approximately $208 per square foot. The property is fully leased to a global manufacturing and technology firm with 5.8 years of term remaining and was acquired at an in-going yield of 5.4% with strong annual rental escalations. Built in 2025 with a 40-foot clear height, the building is near Highway 290 and Beltway 8.
On August 21, Granite acquired 16333 State Highway 249, a roughly 200,000-square-foot distribution facility, for $33.3 million (US$24.2 million), or approximately $167 per square foot. The property is fully leased to two tenants with a weighted average lease term of 3.0 years and was acquired at an in-going yield of 5.3%. It was built in 2023, has a 32-foot clear height and has immediate access to Highway 249 and Beltway 8. The property benefits from strong annual rental escalations and a near-term mark-to-market rent opportunity of approximately 15%.
United Kingdom Distribution Acquisitions Close After Quarter-End
Following the end of the third quarter, Granite closed two UK acquisitions. On October 9, 2026, it acquired Unit 2 Mountpark Bardon in Coalville for $80.4 million (£42.6 million), or approximately $268 per square foot. The roughly 300,000-square-foot facility, built in 2016 with a 49-foot clear height, is fully leased to a leading local third-party logistics company with 6.1 years of term remaining. It was acquired at an in-going yield of 5.4%, with a customary market adjustment in just over a year and an expected stabilized yield of approximately 6.7%. The property is close to the M1 motorway in the area known as the Golden Triangle, one of the UK's premier regional distribution areas.
On October 30, 2026, Granite acquired 1 Barclay Way in West Thurrock for $52.7 million (£28.2 million), or approximately $264 per square foot. The roughly 200,000-square-foot, fully bonded facility was built in 2016, has a 43-foot clear height and is leased to a national distributor with 12.9 years of term remaining. It was acquired at an in-going yield of 6.0%, with a customary market adjustment in less than three years at which point it is expected to yield approximately 7.0%. The property has direct access to the M25 ring road and is close to the Port of Tilbury, the principal port for London.
Separately, on October 1, 2026, Granite completed the sale of a 500,000-square-foot income-producing property in Plainfield, Indiana, for a gross price of $55.0 million (US$38.6 million), or approximately $110 per square foot. The asset had been classified as held for sale at September 30.
Market Context for Houston and UK Industrial
Houston's industrial market has been absorbing a heavy construction pipeline. One third-quarter 2026 assessment reported 27.9 million square feet of deliveries against 20.9 million square feet of net absorption, pushing vacancy to 7.4% and lowering asking rents 1.8% year over year. Another report put vacancy at 6.3%, with warehouse and distribution asking rents at $7.93 per square foot, up 4.2% year over year. Granite's Houston yields of 5.3% and 5.4% compare with a reported overall Houston industrial cap rate of 7.9%, though the acquired assets are newer and fully leased.
In the UK, big-box take-up reached 21.8 million square feet year to date in 2026, ahead of the 10-year pre-pandemic average, while speculative development deliveries were expected to be at their lowest level since 2018. UK industrial rents were rising approximately 4.3% annually, and prime big-box rents increased 2.7% year over year. The Midlands accounted for roughly 63% of big-box take-up in one 2026 review, with retail, e-commerce and fulfillment users representing 78% of activity. Knight Frank reported a UK industrial equivalent yield of 6.27% in July 2026, and Colliers reported prime distribution yields of approximately 5.25% and an overall industrial equivalent yield near 6.2%.
Third-Quarter 2026 Results and Distribution Increase
Granite reported net operating income of $136.0 million for the third quarter, up from $127.1 million a year earlier, citing new and renewal leasing activity mostly in Canada and the United States, contractual rent adjustments and CPI-based increases, and acquisitions of eight income-producing properties in the US and UK beginning in the fourth quarter of 2025, partially offset by six dispositions. Constant currency same property NOI on a cash basis rose 6.9%.
Funds from operations were $99.5 million ($1.60 per unit), compared with $89.9 million ($1.48 per unit) a year earlier. Adjusted funds from operations were $90.3 million ($1.45 per unit), compared with $77.0 million ($1.26 per unit). The AFFO payout ratio was 61%, down from 67%. Net income attributable to unitholders was $78.2 million, compared with $68.0 million.
Granite recognized net fair value losses of $16.4 million in the quarter, including an asset held for sale, attributed primarily to expanded discount and terminal capitalization rates at select European properties, lower fair market rents at select Canadian properties and vacancy at a US property, partially offset by a fair value gain on an asset held for sale in the United States.
The trust raised its targeted annualized distribution by 4.23% to $3.70 per unit ($0.3083 per month) from $3.55 ($0.2958 per month), effective with the December 2026 distribution payable in mid-January 2027.
Portfolio Operations and Balance Sheet
In-place occupancy was 96.7% at September 30, 2026, down 130 basis points from June 30 and 10 basis points from a year earlier. Committed occupancy was 97.0% as of November 4. New leases and renewals totaling approximately 1.6 million square feet achieved average rental rate spreads of 35% over expiring rents.
Granite reached substantial completion in the third quarter on a 0.4-million-square-foot build-to-suit facility in Houston for a global consumer food product company, with full completion and occupancy expected in the fourth quarter. The tenant also agreed to a 0.1-million-square-foot expansion, expected to be occupied in the second quarter of 2027. After quarter-end, Granite signed a new 125-month lease for approximately 0.8 million square feet in Locust Grove, Georgia, with a national e-commerce distributor, replacing a lease that had been due to expire in 2031. The new lease represents a mark-to-market increase of more than 70%.
At September 30, the fair value of investment properties was $9,733.8 million, total debt was $3,191.5 million and the net leverage ratio was 32%, compared with 35% at year-end 2025. Granite owned 140 income-producing properties totaling 61.9 million square feet. The trust is maintaining its 2026 guidance and further tightening the ranges, assuming the $300 million of senior unsecured debentures maturing December 11, 2026, are refinanced through an unsecured term loan at an interest rate slightly below 4.0%.
Granite ranked 3rd of 8 in its GRESB North America industrial listed peer group, with an overall score of 78.5, and received a score of 100 on its GRESB 2026 Public Disclosure Report.
Sources
Granite REIT press release, November 4, 2026: https://granitereit.com/news/granite-reit-announces-2026-third-quarter-results-the-closing-of-2705-million-of-new-acquisitions-and-a-42-distribution-increase-commencing-in-december-2026
More Property Transactions
JLL Income Property Trust Buys Northborough Distribution Center for $36M
CPP Investments, Dream Industrial REIT and Dream Asset Management Complete C$585.8 Million GTA Industrial Acquisition
BGO Strategic Capital Partners Takes Stake in GREYKITE's Uniqhomes UK Single-Family Rental Platform